Purchase
Buying as a first-time home buyer or moving to a new property. Advice is built around your short- and long-term financial and life goals — the best mortgage for your situation, not just the best rate.
Purchase financing
A Canadian mortgage broker, lender, developer and capital markets dealer. Canadians are stuck in debt while banks make record profits on the backs of hard-working families.
In 20+ years and thousands of mortgage applications, I’ve helped clients reach financial freedom — not just with the lowest mortgage rates, but by building cashflow strategy into the long-term plan.
This is a relationship. I don’t get transferred to another branch and I don’t quit. Whether you’re trying to save money, get approved, clean up debt or build wealth, my reliability is the part that is guaranteed.
A mortgage renewal strategy is more than the rate. Your bank sends one offer; a broker shops 65+ lenders, compares the terms behind the rate, and structures the file so more of every payment lands on principal instead of interest.
Pick a 10-minute window.
When was the last time your bank or broker called you to save you money?
Discover the best mortgage rates and lowest mortgage rates in Canada at RateShop. Compare Canadian mortgage lending rates from top lenders to secure your ideal home loan deal today.
Solutions are not created by submitting your application to a dozen lenders and hoping something sticks. Options are curated with precision and leverage, working with lending partners to find flexibility. Knowing the criteria is just the starting point.
Speed to approval, rate negotiation, and protecting your interests while making sense of refinance versus renewal is where the thousands of dollars actually are.
The choice between a three- or five-year term, fixed or variable, and a 25- or 30-year amortization is a lifestyle decision. That is the part we work through together.
RateShop Mortgage helps buyers, homeowners and investors compare rates across 65+ lenders instead of relying on one bank. A bank offers only its own products; a broker can shop multiple lenders, negotiate terms and structure the file around your income, credit and goals.
| What matters at renewal |  RateShop |
Big 5 | Others |
|---|---|---|---|
| 65+ lender access | Yes | No | Sometimes |
| 98% funding rate | Yes | No | No |
| Canada-wide funding | Yes | Yes | Sometimes |
| 48-hour approvals | Yes | No | Sometimes |
| Upfront best rates | Yes | No | No |
| All credit situations | Yes | No | Sometimes |
| Any income type | Yes | No | Sometimes |
| $1 billion+ funded | Yes | Yes | No |
| Expert deal structure | Yes | No | No |
Comparison reflects RateShop’s own lender panel and service standards. Bank and brokerage practices vary by institution and by file.
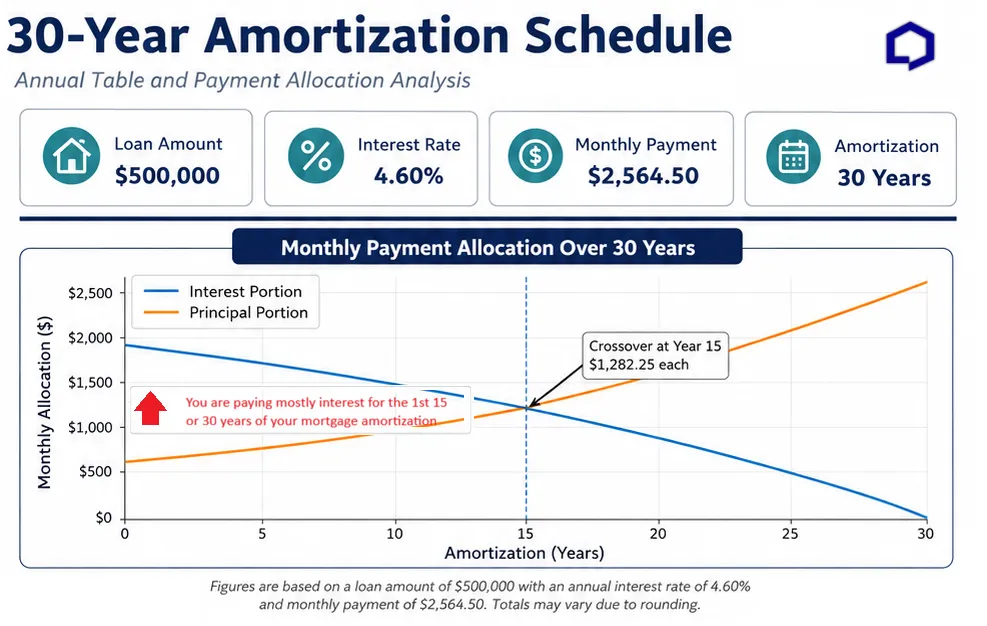
On a standard amortization the early years barely touch principal. Structure is what changes that, not a tenth of a point.
The renewal letter is a retention product. Nobody at the branch is paid to reduce what you pay them.
Prepayment privileges, penalty calculation and porting rules decide the real cost of the next five years.
Term, amortization, shelf and lender choice compound. One decision at renewal outlives the rate on it.
If you think getting a mortgage is like ordering a pizza — extra low interest, heavy on the fixed, bake for three or five years — I’m not the guy to call.
I’ve helped clients save thousands on their mortgages, create consistent passive income, pay their balance down three times faster, and get out of trouble.
My experience stretches across clients earning over $50M annually and others twelve months behind on payments, credit scores from 400 to 900, residential, commercial, development and construction — in Canada and cross-border in 48 states.
Buying as a first-time home buyer or moving to a new property. Advice is built around your short- and long-term financial and life goals — the best mortgage for your situation, not just the best rate.
Purchase financingTo get out of debt you have to understand good versus bad debt. Brokers throw in car loans just to get paid more. You didn’t get here overnight — we stop the bleeding, then show you step by step how it’s done.
Refinance optionsYour bank offered 0.15% lower because you paid them 40% of your income for five years, 90% of it interest. Still want to run the hamster wheel, or is it time for a change? Let’s talk.
Renewal reviewBuying an investment property or building a portfolio? Bring financial-planning experience into the deal structure — purchase under a corporation, tax efficient, and friendly to mortgage qualification.
Rental financingMixed-use, office and specific-use purchases and refinances die on the underwriting table before they get a chance, on poor deal structure. Experience, contacts and structure win these files.
Commercial financingFrom land purchase financing to site plan, permits and construction funding. Funded projects from $2M to $150M — retail and office, CMHC MLI Select, condo builds, subdivisions, mezzanine and syndication.
Development capitalCashflow is what runs the kingdom. Tax-efficient, hands-off investment generating stable returns with liquidity — money in your pocket to pay down your mortgage or build wealth.
Private mortgage investingAs an exempt market dealer we put private capital behind builder projects, REITs and mortgage investment firms. From offering memorandum to prospectus — scale faster, cheaper and compliant.
Talk to the capital deskPick the subject and the booking form opens with it already chosen. Ten minutes is enough to tell you whether there’s money on the table — and if there isn’t, I’ll say so.
This section belongs to our clients. Our commitment is to deliver, to teach stability and better money management, and to build a progress plan that gets you mortgage-free faster. The chance to do that, and to help our communities, is why we go to bat every day no matter how tough it gets.
They were on the ball. They messaged me all the time, they talked to me, I talked, they answered the phone — which is very rare. Answered my question, did what I asked, responded. It was just great.Frank, Barrie, Ontario
This was a complicated one, and as I’ve said to Ali multiple times, he went above and beyond. He was always reachable no matter what time and how I was feeling, and there were a lot of ups and downs.Lisa, Ontario
It’s been so smooth — I’m kind of expecting something not smooth to happen, because there’s usually a hiccup whenever you’re putting together business deals of one form or another.Nathan, Toronto, Ontario
It was a simple, easy process — like you say. Explained it quite simply and understandably, and got it done.Paul, Burnaby, BC
Attention deficit and hyperactivity is a genetic disorder that only worsens when exposed to trauma. In an age of media, screens and busy schedules it can be hard to spot a fight-or-flight response, which leaves a child misunderstood.
You can never blame a child for their responses; they build coping mechanisms around your behaviour and the anxiety transferred onto them. It isn’t curable, but it is treatable — and it isn’t limited to kids.
CADDAC offers connections to resources that help you manage one day at a time and clear up confusion about affected behaviour.
If you or someone you love has been affected by ADHD, or you struggle to identify the patterns, let’s connect here.
A mortgage renewal strategy is the decision set behind the rate: the term length, the amortization, the prepayment privileges, and which lender your file is placed with. Those choices decide how much of each payment reduces your balance, and they outlast whatever rate you sign.
Start about 120 days out. Most Canadian lenders will hold a rate for you 90 to 120 days before maturity, so shopping inside that window costs nothing and gives you a real alternative to the bank’s letter. Leaving it to the last fortnight removes every option but signing.
Yes. At maturity your term has ended, so there is no prepayment penalty for moving. A switch still involves discharge and legal or appraisal costs, and many lenders cover them on a straight transfer. Leaving mid-term is different and does carry a penalty.
No. Two mortgages at the same rate can cost very different amounts depending on how the penalty is calculated, what prepayment you are allowed, and whether the mortgage is portable. A rate a few basis points lower can be the more expensive mortgage over five years.
On a prime mortgage, no. The lender pays the broker on completion, so the borrower pays nothing for the advice or the placement. Fees apply on alternative and private lending, and they are disclosed in writing before you commit to anything.
Your renewal date, your current balance, and roughly what your home is worth. That is enough to tell you which lending shelf your file prices on and whether there is money on the table. If there isn’t, you will be told that on the call.
Ten minutes on the phone. You’ll get the rates you actually qualify for across 65+ lenders, and what the term and amortization choice costs you over the next five years.